

St. Louis Fed President Alberto Musalem said Tuesday that the economy will likely need several rate increases before spring 2027 to bring inflation back to 2% (CNBC). CNBC reads his math as pointing to as many as four hikes, one at each meeting in December, January, March and April (CNBC). One day earlier, Fed Chair Kevin Warsh told a San Francisco Fed audience that an AI-driven burst of innovation could keep U.S. growth well above its long-run average (FT).
The same day Musalem spoke, two data points showed why. Overall import prices jumped 1.1% in October and 9.1% from a year earlier (Wolf Street). Retail sales growth cooled to 0.2% from 0.8% in September (Barron's).
The AI story has pushed stock valuations up (CNBC). The question for regular investors: can the productivity payoff arrive before the next round of inflation does?
The Fed Has Moved From Cuts to Hikes
Musalem frames it around the real policy rate, which is simply the Fed's rate minus inflation. The St. Louis Fed chief wants it at 2% to 2.5% by next spring and puts it today at the low end of 1% to 1.5% (WSJ). In his view, falling inflation probably won't close that gap on its own. Rate hikes will have to do most of it.
A few facts for context:
The Fed raised rates in September for the first time in three years, to a 3.75%-4% range (WSJ). It held steady last month (WSJ).
Markets put 96% odds on a quarter-point hike in December and about 4% on a half-point move, per LSEG (WSJ).
Musalem won't vote until 2028, but he still shapes the Fed's dot plot of rate projections (CNBC).
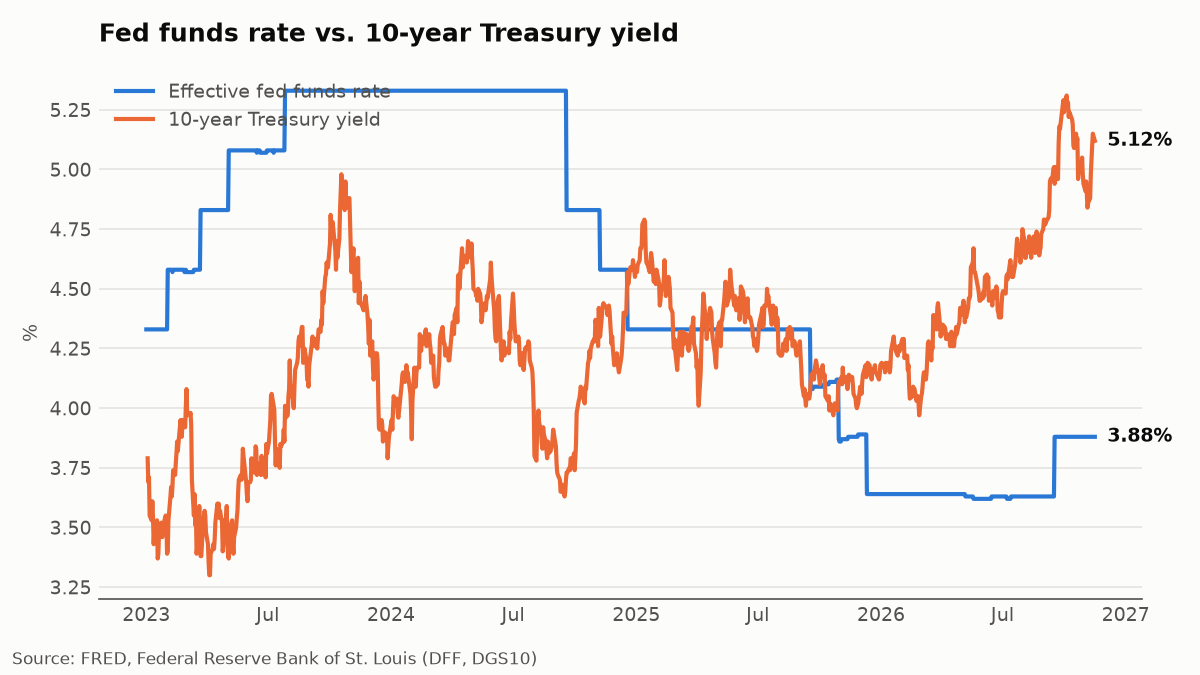
The effective fed funds rate held flat at 3.88% in November. The 10-year Treasury yield climbed from 4.84% on November 5 to 5.15% on November 13, then ended at 5.12% on November 16.
The Second Wave Is Showing Up in Import Prices
Wolf Richter calls October's import report part of a second wave of inflation. The numbers back him up (Wolf Street):
Imported computers, peripherals and semiconductors rose 3.6% from September and 26.9% from a year earlier.
Import prices for all manufactured goods rose 0.8% on the month and 7.2% on the year.
These figures exclude tariffs, which come on top.
The increases ran across energy, capital goods, metals and consumer products. Only food stayed calm.
One caution: the 2025 government shutdown left no October 2025 index value. Richter estimated it by averaging September and November, so the yearly figures are approximations.
The twist is the AI link. Electronics used to drag inflation down because they got cheaper every year. Richter argues that chip and GPU demand from the data center buildout has reversed that.
Richter places this alongside producer prices up 6.5% and consumer prices up 4.0% from a year ago. The WSJ notes that AI has fed expectations of higher rates because it adds to demand while the Iran war pushes up input costs (WSJ).
Retail Sales: Slower Headline, Firm Core
How can spending look solid if households are pulling back? Look underneath. The headline 0.2% matched forecasts. But the control group rose 0.6% against a 0.4% estimate (Barron's).
The control group strips out autos, gas, building materials and restaurants, and it feeds into GDP. IBD says the data strengthened the case for a hike (IBD).
Some of that strength is just higher prices in disguise. Gas station sales rose 30% from a year earlier because gasoline prices jumped 37% (Wolf Street).
Bank of America card data showed spending per household up just 0.1% in October. Morgan Stanley expects consumer spending growth to slow to a 1.6% annualized pace this quarter, down from 3.8% in the third (Barron's). Some economists think the boost from tax cuts is fading (WSJ).
Opposing Views
The Bull Case
Warsh argues AI could change both how ideas are generated and how quickly. If Warsh is right, faster growth could last without stoking inflation (FT).
Even Musalem sketched an unlikely but possible path with no more hikes. In Musalem's scenario, cheaper energy and shipping, or faster productivity growth, could pull inflation toward target within 18 months (CNBC).
Prediction market Kalshi puts U.S. productivity growth at 2.2% over five years (Marginal Revolution). Tyler Cowen thinks it will come in somewhat higher (Marginal Revolution).
The Bear Case
The Fed chair himself admits the payoff hasn't arrived. Productivity "hasn't yet broken out definitively and structurally to the upside," Warsh said (FT). One of the Fed staff's own scenarios has AI returns disappointing, stock valuations falling, and unemployment rising (CNBC).
Richter argues the AI buildout is itself a driver of inflation right now (Wolf Street). Markets are already flinching. The S&P 500 fell 1% Tuesday (WSJ), and a major software ETF dropped more than 3% (IBD).
Conclusion
The AI boom is pushing up prices today. The productivity gains that could offset them are still a forecast. The Fed is pricing in the first effect.
A December hike looks nearly certain; the real debate is how many follow into 2027.
Import prices, especially electronics, are the inflation data to watch, and they exclude tariffs.
Headline retail sales slowed, but the GDP-linked core beat expectations, which keeps pressure on the Fed.
Warsh's AI optimism is a long-run argument; he concedes productivity hasn't broken out yet.
Sources
Fed’s Musalem Says Several Rate Hikes Likely Needed Before Spring 2027 - WSJ, 2026-11-17
St. Louis Fed's Musalem says four more rate hikes may be needed in coming months - CNBC, 2026-11-17
Second Wave of Inflation: Import Prices Spike across the Board, Prices of Imported Electronics Explode - Wolf Street (RSS), 2026-11-18
Slower Retail Sales Drag on Market - WSJ, 2026-11-17
Retail Sales Held Up in October, but Holiday Spending Looks Shaky - Barron's, 2026-11-17
My Thoughts about those Retail Sales in October - Wolf Street (RSS), 2026-11-17
Warsh says AI boom could help sustain ‘substantially higher’ US growth - FT, 2026-11-16
Warsh Says Fed Is Gaming Out How AI Could Reshape Economy - WSJ, 2026-11-16
Fed Chairman Kevin Warsh stresses importance of AI to economy, but says it could ‘disappoint’ - CNBC, 2026-11-16
U.S. Treasury, Eurozone Bond Yields Edge Lower as Fresh Drivers Are Sought - WSJ, 2026-11-17
Software Stocks Retreat Amid Inflation Worries, New OpenAI Model - IBD, 2026-11-17
The Kalshi market on U.S. productivity growth - Marginal Revolution (RSS), 2026-11-17
Fed funds rate vs. 10-year Treasury yield - Source: FRED, Federal Reserve Bank of St. Louis (DFF, DGS10)
Fed funds rate vs. 10-year Treasury yield - Source: FRED, Federal Reserve Bank of St. Louis (DFF, DGS10)
Thanks For Reading!
If you have any source you wish to see in our lineup, please reach out and let us know.
It's been a while since our last issue. If these emails aren't for you anymore, you can unsubscribe here, no hard feelings.
Musalem's schedule, December through April, lines up almost exactly with the window in which the last productivity boom ran out of road.
In the late 1990s Greenspan was the one making Warsh's argument. He talked up productivity for years, and the Fed still hiked six times between June 1999 and May 2000, to 6.5%. The Nasdaq peaked on March 10, 2000, nine months after the first hike. Nobody stoped believing in the internet. Money just got too expensive for the companies that needed it.
Count nine months from this September's hike and you land in mid-June 2027. Musalem's four hikes would be done by April. So your question, whether productivity arrives before the next round of inflation, has a deadline, and it's a lot closer than the five-year productivity forecasts.
The difference from 2000 is who is borrowing. Two years ago net new debt covered about 9% of the capex at Microsoft, Amazon, Alphabet, Meta and Oracle. In the twelve months to mid-2026 it covered 32%. Each hike now lands on the very build-out that's supposed to deliver Warsh's productivity, and it lands there well before it reaches import prices.
For an investor the number to watch isn't December, which is 96% priced. It's the 10-year. As long as it sits above 5%, and it was 5.12% on Monday, the runway keeps getting shorter whatever the AI headlines say.