

The Fed held rates steady in October, but the minutes released Wednesday show that pause was a breather, not a finish line. Officials saw more rate hikes as the likely route to returning inflation to the 2% goal in a timely way (CNBC).
A couple said December could justify more than a quarter point if inflation data ran hot (CNBC, FT). It did. October CPI rose 0.4% overall and 0.3% at the core, each 0.1 percentage point above forecasts (CNBC).
Governor Christopher Waller told CNBC a half-point hike is probably needed at the Dec. 8-9 meeting. Waller added that the Fed may need to jolt the public out of complacency (CNBC).
Bonds got the message. The 10-year Treasury yield last traded at 5.084% Thursday, and money markets now put an 8% chance on a half-point move, up from 2% on Wednesday (WSJ). The 30-year mortgage rate rose to 7.35% from 7.21% (CNBC).
The Hawks Say Inflation Is Leaking Everywhere
The committee voted 10-2 in October to hold at 3.75%-4%, with Lisa Cook and Beth Hammack wanting a quarter-point hike right away. The bigger worry in the room was breadth. Officials described inflation pressure as broad based and named the AI build-out a significant inflation risk (CNBC). Per the FT, several saw price pressure moving past the industries tied directly to data center construction (FT).
Waller was blunt: "I'm very, very concerned about inflation. It's kind of headed in the wrong direction, and it's spreading out" (CNBC). Waller wants to undo the three insurance cuts of 2025 and possibly go further.
The pipeline data back him up:
Wolf Richter reports import prices for computers, peripherals and semiconductors jumped 3.6% in October from September and 26.9% from a year earlier (Wolf Street).
Overall import prices rose 1.1% on the month and 9.1% on the year, with gains from petroleum to capital goods to consumer products. Only food stayed calm (Wolf Street).
Andrew Wilson of the International Chamber of Commerce told the WSJ that consumer-goods makers' costs could run 10% to 12% above prewar levels, peace deal or not (WSJ).
S&P Global's October surveys showed manufacturers' input costs climbing at the fastest pace since June (WSJ).
St. Louis Fed President Alberto Musalem figures the policy rate sits only about 1 percentage point above inflation (WSJ). Musalem suggests it may need to be 2 to 2.5 points above (WSJ).
Why Bonds Think the Economy Can Take It
The Fed is talking about shock therapy. So why is the bond market growing calmer about AI risk?
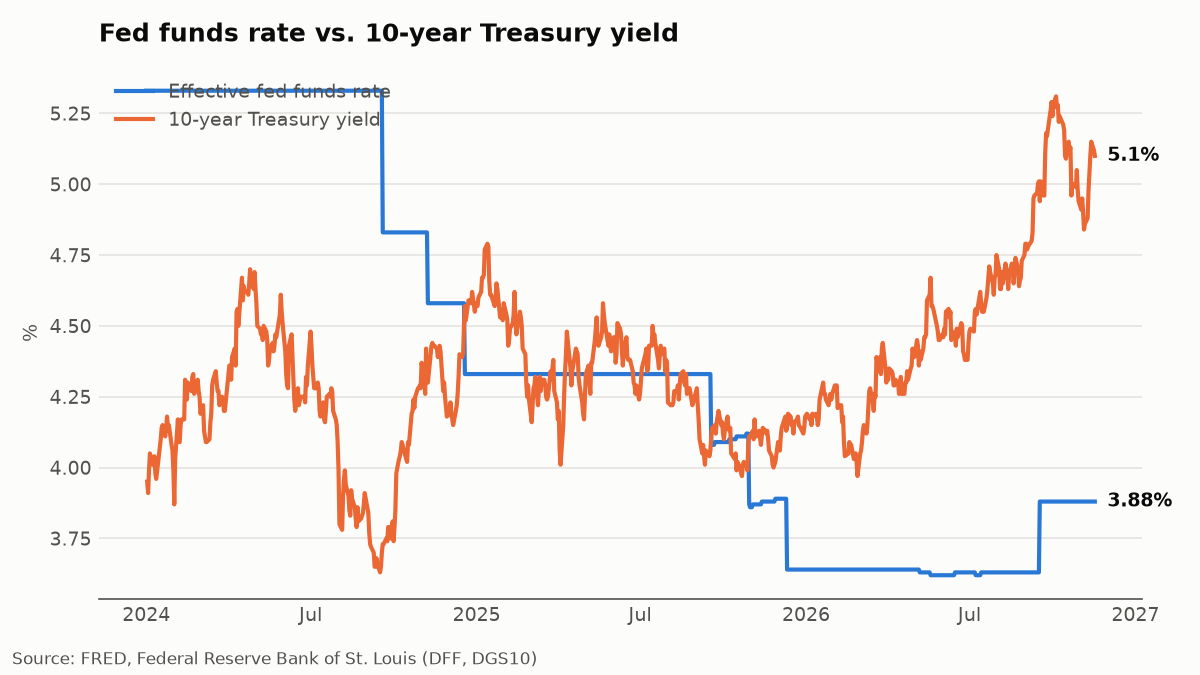
The effective fed funds rate stayed parked at 3.88% through mid-November while the 10-year yield rose from 4.84% on Nov. 5 to 5.15% on Nov. 13, settling at 5.1% on Nov. 17.
The WSJ's Telis Demos notes that last week, spreads on Alphabet, Amazon and Meta bonds narrowed more than those on other corporate bonds (WSJ). Demos adds that data-center bond spreads have tightened since Nov. 9 (WSJ). A spread is the extra yield investors demand over Treasurys, so narrowing means less fear.
Growth is solid too: Moody's says real GDP grew at a 3.4% annualized pace in the third quarter and expects 2.3% for the year (WSJ). Anthropic's $81 billion IPO had Nasdaq futures up 2% premarket Thursday (WSJ).
That strength is the trap. Tickmill's Patrick Munnelly argues officials liked seeing markets tighten for them, so an AI-driven loosening of financial conditions could draw a tougher Fed response (WSJ). A hot AI rally may invite more hikes, not fewer.
Where the Damage Shows Up First
Duration. The 2-year yield, the one most tied to the Fed outlook, rose to 4.81% Wednesday (IBD). JPMorgan expects Thursday's $19 billion 10-year TIPS sale to need a bigger concession (WSJ). Barron's adds a debt ceiling fight: the limit of $41.1 trillion could be reached in February or March (Barron's).
Housing. Mortgage applications fell 2.3% in a week. Purchase applications were 18% below a year ago, refinancing 54% lower (CNBC).
Richly valued tech. Fed staff warned that off-balance-sheet leases and circular financing among AI firms could magnify losses if AI returns disappoint, and most officials flagged fast-growing AI debt in opaque structures (CNBC).
Opposing Views
The Bull Case
Eurodollar University argues the TIPS market rejects Waller: longer-dated inflation expectations price little chance the energy shock spreads, because consumers aren't strong enough to swallow price pass-through. The host compares it to 2008, when Fed officials feared a spillover that never came (YouTube). WSJ's Nick Timiraos notes markets are already tightening for the Fed, with AI stocks pulling back, oil falling and refiner margins shrinking (WSJ). New York Fed President John Williams sees no need for dramatic action, and officials still expect inflation to drop sharply in 2027 (CNBC).
The Bear Case
Pipeline costs say this isn't over. The ICC's Wilson expects supply-chain pressure to keep inflation elevated for months (WSJ). Waller has cited diesel prices that won't ease as fast as crude (WSJ). The minutes warn that waiting risks entrenched inflation or a bigger, more disruptive tightening later (WSJ).
Futures already price a quarter point in December, another hike in January and at least one more before the end of 2027 (CNBC). The FT may pull its third-hike forecast forward from March to January (FT).
Conclusion
The tightening cycle is speeding up. A strong economy and a hot AI trade give the Fed more reason to push, not less.
Treat a December hike as done; the real question is size and how soon the next one follows.
Long-duration bonds remain exposed to hawkish surprises and debt ceiling noise.
Housing is the clearest casualty, with mortgage rates at a three-week high and purchase applications 18% below a year ago.
Rich AI and tech valuations face both higher rates and Fed scrutiny of opaque AI debt.
Watch import prices and producer costs; they lead what shows up in CPI.
Sources
Fed’s October minutes confirm December increase and float faster tightening - FT, 2026-11-19
Fed officials expect more rate hikes, worry about AI impact on inflation, minutes show - CNBC, 2026-11-18
Fed Officials Saw Higher Rates Ahead When They Held Steady Last Month - WSJ, 2026-11-18
Fed’s Waller says central bank may need to ‘shock people’ with half-point rate hike - CNBC, 2026-11-18
Fed Gov. Waller: 'Shock' Rate Hike May Be Needed With Inflation 'Spreading Out' - IBD, 2026-11-18
Cost Pressures Already in Pipeline to Fuel Higher Inflation - WSJ, 2026-11-18
Second Wave of Inflation: Import Prices Spike across the Board, Prices of Imported Electronics Explode - Wolf Street (RSS), 2026-11-18
Treasury, Eurozone Bond Yields Edge Higher - WSJ, 2026-11-19
Mortgage demand turns lower, as interest rates shoot back up to the highest level in three weeks - CNBC, 2026-11-18
The Debt Ceiling Arrives Early Next Year. It Could Hit Bonds. - Barron's, 2026-11-18
The Bond Market’s Surprising Take on the AI Trade - WSJ, 2026-11-19
Moody’s Says U.S. Economy Grew More Than Expected - WSJ, 2026-11-18
Markets Are Being Liquidated...Here’s What’s Really Happening - Eurodollar University (YouTube), 2026-11-19
Fed funds rate vs. 10-year Treasury yield - Source: FRED, Federal Reserve Bank of St. Louis (DFF, DGS10)
Fed funds rate vs. 10-year Treasury yield - Source: FRED, Federal Reserve Bank of St. Louis (DFF, DGS10)
Thanks For Reading!
If you have any source you wish to see in our lineup, please reach out and let us know.
It's been a while since our last issue. If these emails aren't for you anymore, you can unsubscribe here, no hard feelings.
Look at what's in the import numbers: computers, peripherals and semiconductors up 26.9% in a year. A lot of that is the AI build-out buying its own equipment, plus tariffs. Raising rates won't make an imported GPU any cheaper.
So the only way a hike brings that inflation down is by slowing the build-out, through the money that funds it. And right now the build-out is what's holding growth up. In Q3 real GDP grew 3.4% annualized, equipment investment 20.9%, and residential investment fell 3.3%. Housing is already on its back, purchase applications are 18% below a year ago as you note, so there's not much left to squeeze there.
That's why I read "shock therapy" differently. A 50bp hike in December isn't really aimed at the consumer. In practice it makes data-center money more expensive until hyperscalers trim capex, and maybe that's even the point, to cool the AI trade on purpose. The minutes don't say it, but that's the channel the hike works through, and capex is exactly the piece that could turn a slowdown into a recession.
If you're positioning for December, I'd worry less about housing names, they're already priced for pain, and more about the companies that sell into the build-out.
The off balance sheet leasing line jumped out at me. Most leases have sat on the balance sheet since ASC 842, but one only lands there at commencement, so signed data center deals that haven't started live in the footnotes