

Treasury yields flipped higher on Monday, with the 10-year up 0.9 basis points to 4.869% after starting the day lower (WSJ). Traders are done trading the midterms. Now they're watching Tuesday's October consumer price index and Friday's producer price index, plus a run of long-dated Treasury auctions.
That shift follows an ugly week for stocks. The Nasdaq Composite fell 5.5% on Thursday, its worst day since the April 2025 tariff turmoil. The S&P 500 posted its fourth weekly loss in a row (Barron's).
Chip stocks led the selling on fears a Democratic Congress will slow data-center construction. The question for regular investors: after the AI rout, are long-term rates and tighter liquidity the next shoe to drop?
Washington's Bark Is Louder Than Its Bite
The headline story is that Democrats now threaten Trump's grip on the Fed and the banks:
A Democratic Senate can block Trump's picks for the Fed board. Investment manager Mark Spindel said Trump's chance to reshape the Fed's relationship with the White House "clearly died Tuesday" (WSJ).
But Trump has appointed only three of the 12 rate-setting voters. The Warsh-led Fed already went against his wishes, hiking in September for the first time since 2023 (same source).
Bank stocks barely flinched. WSJ's Telis Demos notes the KBW Nasdaq Bank index is down 1.7% since the election, versus about 2.5% for the S&P 500 and over 11% for the PHLX Semiconductor index. Fed supervision chief Michelle Bowman and Chair Kevin Warsh hold those roles through 2029 and 2030 (WSJ).
Mostly, the politics just lock in an independent Fed with a hawkish lean. Markets now see an 81% chance of a December hike, up from roughly 72% before Friday's jobs report, per LSEG data cited by WSJ. Employers added 165,000 jobs in October (AP), nearly triple expectations. Unemployment stood at 4.1% (Real Investment Advice).
The Real Tell: Yields Rising While Oil Falls
How can yields turn up if the biggest inflation driver is getting cheaper? Brent crude fell 3.5% to $94.93 on Monday and WTI dropped 3% to $88.13 after Trump played down further strikes on Iran (WSJ). AP reports crude plunged after the midterms on hopes Democrats push to end the conflict, the same war that has kept CPI running above 3% since March (AP).
Cheaper oil should pull long yields down. If the 10-year rises anyway, the bond market is saying its worry goes beyond energy: sticky inflation elsewhere, heavy Treasury supply, or both.
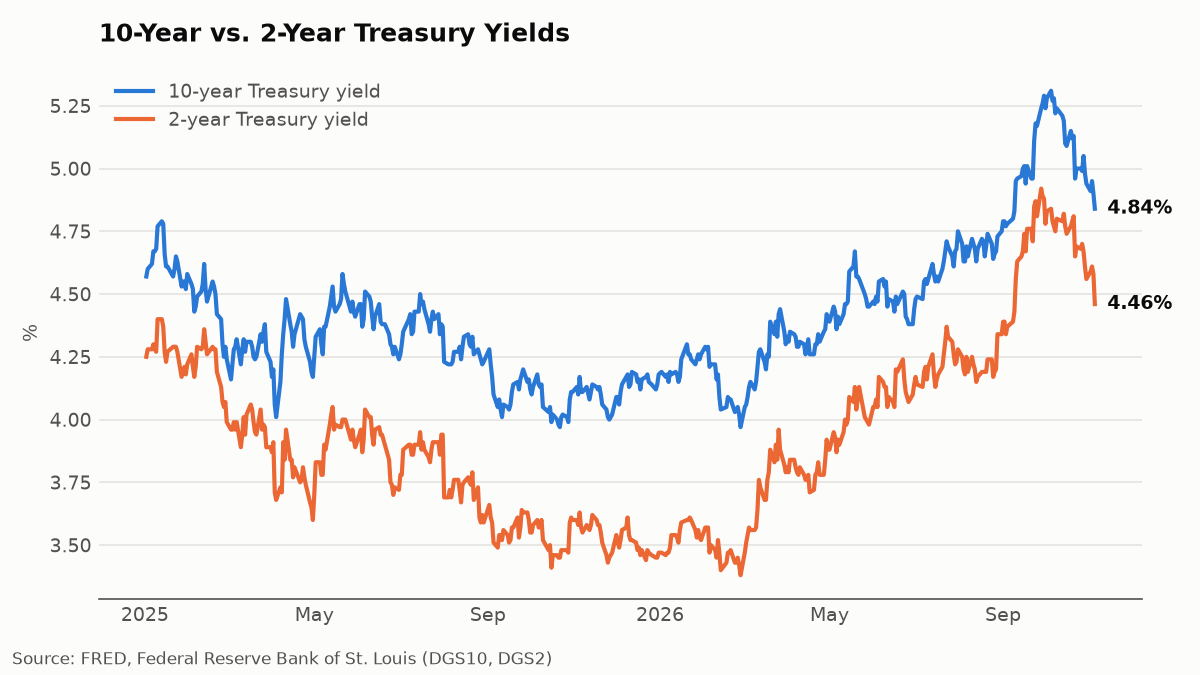
The 10-year eased from 5.13% on October 21 to 4.84% on November 5, while the 2-year slipped from 4.81% to 4.46% over the same stretch.
Wolf Richter of Wolf Street puts that rally in context. The 10-year closed at 5.31% on October 5, and the October 7 auction cleared at 5.30%, the highest auction yield since November 2000. The 45-basis-point slide since then, to 4.86% on Friday, is small next to the 121-basis-point drop of late 2023 or the 105-basis-point drop of mid-2024. If yields head higher from here, Richter argues, it shows the market can't even manage a proper relief rally.
This week is the test. The 10-year auction lands Tuesday, hours after CPI, with the 30-year auction Thursday.
Barron's cites a 0.3% monthly headline CPI forecast after September's 0.6%, with core at 0.2%. RBC expects core at 0.3%, citing three months of accelerating goods prices (FT). Real Investment Advice adds that the recent energy drop probably won't show up until the December reports.
Why Liquidity Is the Bridge to Stocks
Real Investment Advice's liquidity gauge reads -18.73, down from -13.66 a week ago and +5.23 a month ago. Two plumbing signals drive it:
Bank reserves near $2.9 trillion, under the Fed's $3 trillion comfort level.
SOFR, the overnight secured borrowing rate, trading 7-10bps above the effective fed funds rate, an early sign of funding strain.
Real Investment Advice notes falling bond yields have been helping liquidity. Reverse that, and a cushion disappears just as the S&P 500 sits at 7,376.86. That is barely above a 200-day average of 7,325, which the firm calls the level that matters most (Real Investment Advice). Even roughly 29% third-quarter earnings growth hasn't stopped the S&P 500 from sliding 3.6% since early October (Barron's).
Opposing Views
The Bull Case
Crossborder Capital argues the election is modestly bullish for long Treasuries: fewer odds of new tax cuts and more reliance on the Fed if growth weakens (Capital Wars). On AI, JPMorgan Asset Management's Hugh Gimber says "data centre rollout will continue at pace," and S&P 500 futures were up 0.9% Monday (FT).
Jefferies' Mohit Kumar expects "hiccups rather than a derailing of the AI trade" (WSJ). Real Investment Advice found 27 similar oversold setups since 1950; the index was higher a month later 23 times.
The Bear Case
Wolf Richter warns a failed rally could open the next leg of the selloff, and says he won't buy at auctions at these yields. TD Securities sees headline inflation finishing 2026 at 4.0% and core at 2.8% (WSJ).
Friday's PPI is expected at 6.6% year over year (Barron's). Andy Constan told Forward Guidance that AI, onshoring and deficit promises must be funded largely by private credit, not the Fed. Even Crossborder expects 2026's liquidity squeeze to weigh on 2027 growth.
Conclusion
The election grabbed the headlines. The bond market gets the final say on whether last week's AI selloff spreads into something broader.
Watch Tuesday's CPI and 10-year auction together; a weak auction after a hot print is the danger combo.
If oil keeps falling and the 10-year still rises, treat it as a warning, not noise.
Track liquidity plumbing: reserves below $3 trillion and SOFR above fed funds.
The S&P 500's 200-day average near 7,325 is the line between correction and something worse.
Don't overreact to Fed and bank headlines; the Fed's hawkish lean matters more than who sits in Congress.
Sources
U.S., Eurozone Bond Yields Turn Higher as Investors Shift Focus Back to Data - WSJ, 2026-11-09
Would Be a Worrisome Sign for the Bond Market if Treasury Yields Turn Higher Next Week - Wolf Street (RSS), 2026-11-08
Will US inflation data ease affordability concerns? - FT, 2026-11-08
Inflation Data, Constellation Energy, Skydance, Applied Materials, and More to Watch This Week - Barron's, 2026-11-08
Inflation, housing, jobs and corporate earnings will dominate the business calendar this week - AP, 2026-11-07
Liquidity Tightens: Pay Attention, Don’t Panic - Real Investment Advice Ria Bull Bear Report (RSS), 2026-11-09
The Blue Wave Turns Markets Red - Crossborder Capital Capital Wars (RSS), 2026-11-07
The Democratic Surge Will Cap Trump’s Reach at the Fed - WSJ, 2026-11-08
For Big Bank Stocks, Capitol Hill’s Bark Is Worse Than Its Bite - WSJ, 2026-11-09
US stocks set for gains after AI rout - FT, 2026-11-09
Future Growth Will Be Driven By Banks, Not the Fed | Andy Constan - Forward Guidance Blockworks (YouTube)
Oil Slides More Than 3% as Trump Downplays Prospect of New Iran Strikes - WSJ, 2026-11-09
10-Year vs. 2-Year Treasury Yields - Source: FRED, Federal Reserve Bank of St. Louis (DGS10, DGS2)
10-Year vs. 2-Year Treasury Yields - Source: FRED, Federal Reserve Bank of St. Louis (DGS10, DGS2)
Thanks For Reading!
If you have any source you wish to see in our lineup, please reach out and let us know.
It's been a while since our last issue. If these emails aren't for you anymore, you can unsubscribe here, no hard feelings.